How to Calculate Taxes on Paycheck: Gross Pay, Deductions, Withholding, and Net Pay
Learn how to calculate paycheck taxes by understanding gross pay, federal and state withholding, deductions, and net pay.
 Charles Hardy
 Updated on Sep 30, 2026
 10 min read
Scannable summary
Key Takeaways
- Start with gross pay, calculated from hours and pay rate for hourly employees or salary and pay frequency for salaried employees.
- Calculate federal income tax withholding based on the employee’s Form W-4 and applicable IRS withholding rules.
- Deduct FICA taxes, including Social Security and Medicare, using the applicable rates and wage limits.
- Account for state and local taxes and voluntary deductions, including applicable pre-tax deductions.
- Subtract all applicable deductions from gross pay to determine the employee’s net pay, or take-home pay.
To calculate taxes on a paycheck, you start with gross pay, then subtract federal income tax withholding, FICA taxes, any applicable state and local taxes, and voluntary deductions, to arrive at net pay. Each of these steps follows a specific, predictable formula.
Here’s how to calculate it, step by step.
Step 1: Start with gross pay
Gross pay is total earnings before anything is withheld. For hourly employees, that’s hours worked multiplied by the hourly rate, plus any overtime. For salaried employees, it’s the annual salary divided by the number of pay periods in the year.
Example: An hourly employee working 80 hours in a biweekly pay period at $25/hour earns $2,000 in gross pay.
Step 2: Subtract federal income tax withholding
Federal income tax withholding is based on the employee’s Form W-4, which accounts for filing status, dependents, and any additional withholding requested. The IRS provides withholding tables and a Publication 15-T method that employers use to calculate the exact amount to withhold for each pay period, based on gross wages and W-4 elections.
There’s no flat percentage here. Two employees earning identical gross pay can have different federal withholding amounts based purely on how they filled out their W-4.
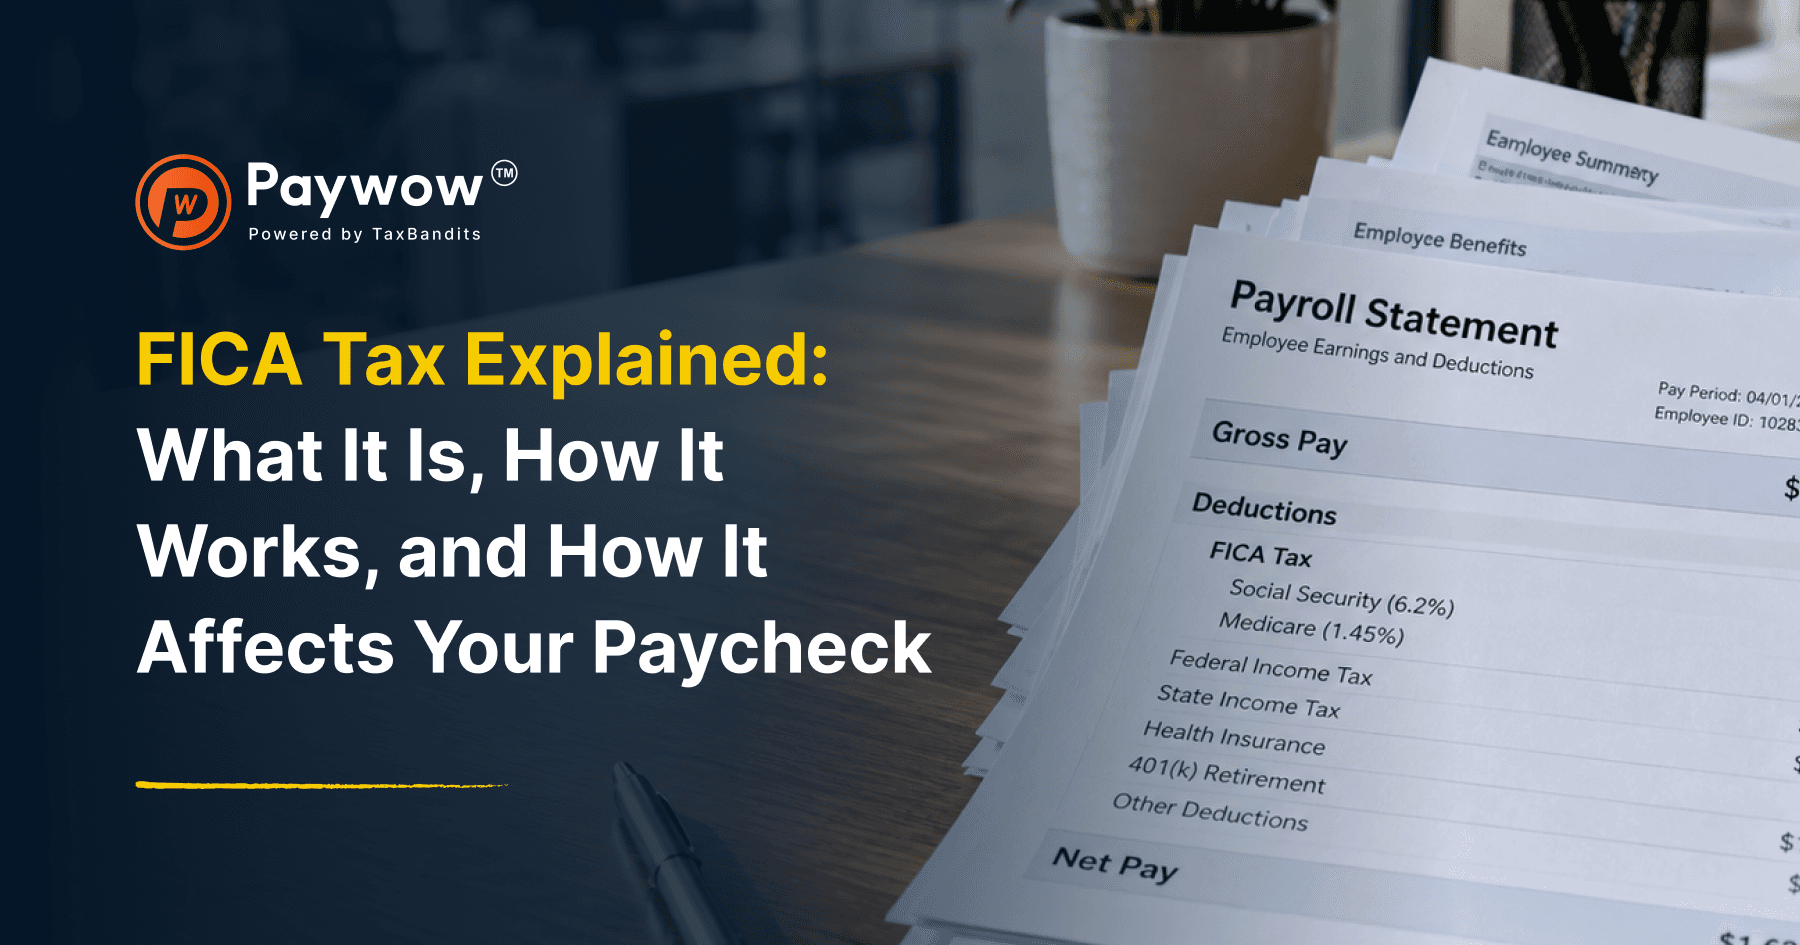
Step 3: Subtract FICA taxes
FICA is the one part of this calculation that’s genuinely predictable, since the rates are fixed by law:
|
Tax |
Rate |
2026 wage base |
|---|---|---|
|
Social Security |
6.2% |
First $184,500 |
|
Medicare |
1.45% |
No cap |
|
Additional Medicare |
0.9% |
Wages above $200,000 |
Example: On $2,000 in gross pay, Social Security withholding is $2,000 × 6.2% = $124, and Medicare withholding is $2,000 × 1.45% = $29, for a combined FICA deduction of $153.
Step 4: Subtract state and local taxes, if applicable
Not every state has an income tax. In states that do, the calculation typically follows a similar withholding-table method to federal tax, based on the employee’s state withholding form and gross wages. Some cities and counties also levy local income taxes, which stack on top of state withholding.
Step 5: Subtract voluntary deductions
These vary by employee and employer, but commonly include:
-
Health insurance premiums
-
Retirement contributions, such as a 401(k)
-
Health savings account (HSA) or flexible spending account (FSA) contributions
Many of these deductions are pre-tax, meaning they reduce the wages subject to federal income tax and, in some cases, FICA, before those taxes are calculated. This is why the order of calculations matters: pre-tax deductions typically apply before, not after, tax withholding is computed.
Step 6: Arrive at net pay
Whatever remains after every deduction is the employee’s net pay, the amount that actually gets deposited.
Putting it all together
Using the $2,000 gross pay example, with no state income tax and no pre-tax deductions for simplicity:
|
Item |
Amount |
|---|---|
|
Gross pay |
$2,000.00 |
|
Federal income tax withholding (example) |
$180.00 |
|
Social Security (6.2%) |
$124.00 |
|
Medicare (1.45%) |
$29.00 |
|
Net pay |
$1,667.00 |

Why manual calculation gets risky
Doing this by hand for one paycheck is manageable. Doing it correctly, every pay period, for every employee, while tracking wage base limits, additional Medicare thresholds, and annual rate updates, is where manual payroll tends to break down. A single miscalculated withholding doesn’t just shortchange the employee’s paycheck, it creates a tax filing discrepancy that surfaces later, often at year-end when W-2s are issued.
The core formula to remember
However complex your specific situation gets, the underlying formula never changes:
Gross pay − federal tax − FICA − state/local tax − voluntary deductions = net pay
Every payroll calculation, no matter how many line items appear on the pay stub, is a variation of that single equation.
The formula is simple until you're running it correctly for every employee, every pay period. PayWow calculates gross pay, withholding, and net pay automatically, so a miscalculated paycheck never becomes a year-end surprise.
Related Blogs